Simple Checkbook Ledger

Screenshots
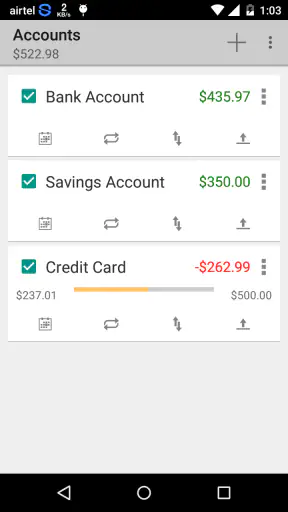
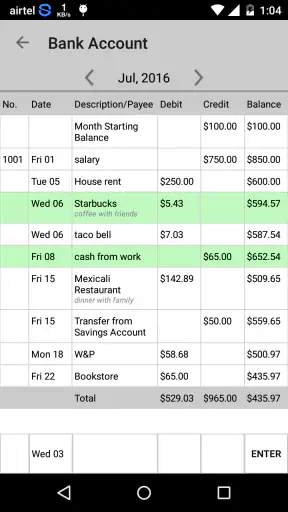
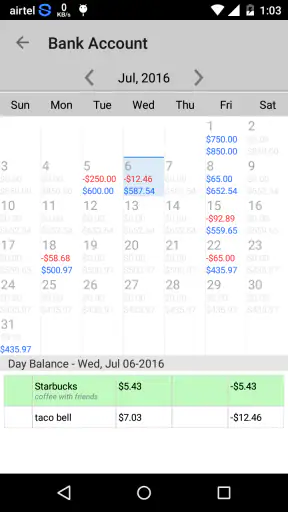
Details
- Rating
- 1.24K reviews
- Version
- 3.5
- Developer
- Teelu Apps
Analysis by Norviv
Simple Checkbook Ledger is the kind of finance app I would recommend to someone who wants a clear record of personal spending without turning money management into a full-time project. I found its appeal in the basic checkbook idea: enter what comes in, enter what goes out, and keep a running view of the balance. That sounds modest beside modern budgeting platforms, but the simplicity is exactly what makes it useful for a certain kind of user.
My overall view is straightforward: this is a focused ledger rather than a complete financial command center. It can help you build a dependable spending habit, especially if you prefer manual control, but it is not the best choice for people expecting automatic bank connections, elaborate reports, or a polished all-in-one budget system. The app is free, comes from Teelu Apps, and is listed for Everyone, so the barrier to trying it is low. The real question is whether a simple ledger matches the way you handle money.
What using the ledger feels like day to day
I find the day-to-day value of a checkbook ledger depends less on how often I open it than on whether I give every entry the same meaning. In this section, I’ll focus on building a repeatable routine—especially around scheduled bills and cash—so the balance stays useful rather than merely looking tidy.
A practical approach to recording money
When I use a checkbook-style app, I am not looking for financial advice or a lecture about spending. I want a place where each transaction has a clear home and where the balance makes sense after I record it. Simple Checkbook Ledger is built around that expectation. Its store summary describes it as a way to manage accounts with ease, while the short description presents it as a simple checkbook ledger. Those descriptions are restrained, and that restraint matches the experience better than claims about transforming your entire financial life would.
The most useful way to approach it is to treat the app as a daily register. I would open it after buying groceries, paying a bill, receiving income, or moving money through an account. Entering the transaction soon after it happens is important because a ledger is only as reliable as the information you put into it. If I wait several days and try to reconstruct every purchase from memory, the app becomes a partial record rather than a trustworthy picture.
A realistic example is a household that uses a checking account for rent, utilities, groceries, and occasional cash withdrawals. Instead of waiting for a monthly statement, one person can record each payment as it happens. The running balance then becomes a quick answer to a practical question: how much money is actually available before the next deposit? That is more useful than simply opening a banking app and seeing a balance that may not account for pending purchases or checks that have not cleared.
This manual approach also gives the user control over how the account is represented. I can think of an entry as a promise, a cleared payment, or a completed withdrawal, depending on the way I keep records. That flexibility is helpful, but it creates a responsibility: I have to use the same method consistently. If I record some transactions immediately and others only after they clear, the balance can become confusing even when every individual entry looks correct.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Why a small ledger can beat a larger budgeting platform
Many finance apps try to connect every account, categorize every purchase, predict future spending, and display colorful charts. Those tools can be valuable, but they also introduce setup work and distractions. Simple Checkbook Ledger makes more sense for someone who wants to see transactions in a direct sequence rather than interpret a dashboard full of summaries.
I especially like the manual-ledger model for people who use one main account and already know their regular bills. A person who wants to record a rent payment, a paycheck, and a handful of everyday expenses may not need automatic importing. In that situation, a lightweight register can be faster to understand than a larger app that asks for categories, goals, account connections, and notification preferences before it becomes useful.
There is also a privacy-minded advantage to manual entry, although it comes with a trade-off. You are not depending on an automatic feed to tell you what happened; you choose what to record and when. That can feel more deliberate and less intrusive. On the other hand, manual entry demands discipline. Users who regularly forget transactions will probably get more value from an alternative that imports activity automatically, even if that alternative feels more complicated.
Three habits that make the app more useful
The first habit I would suggest is recording pending obligations separately in your own routine, even if you do not consider them completed transactions yet. For example, after scheduling a bill, enter it in a consistent way so you remember that the money is already committed. The exact method matters less than applying it every time. This prevents the common mistake of treating the visible bank balance as fully spendable.
The second is to use a short, recognizable note for recurring payments. “Electricity,” “rent,” and “school” are more useful later than vague descriptions such as “payment.” A clean description turns the ledger into a reference tool when you are checking a month of activity. It also makes manual reconciliation less tiring because you can identify an entry without mentally replaying the entire day.
The third is to reconcile on a fixed occasion rather than only when something looks wrong. I would choose a weekly moment, compare the app’s running balance with the account record, and correct mistakes while they are still easy to find. This workflow is particularly valuable for people who make several small card purchases. The app can provide the structure, but it cannot know about a forgotten coffee or an unrecorded cash withdrawal.
The strongest evidence of its value
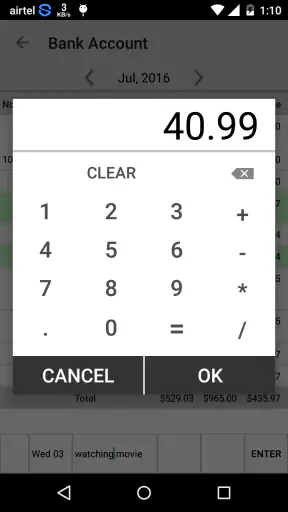
The clearest strength is focus. Simple Checkbook Ledger is not trying to make a small personal register feel like an accounting department. For a user who wants a basic record, that can reduce friction. I can imagine opening it for a few seconds after a transaction, entering the amount and description, and moving on without navigating through a long planning system.
That focus is also useful for people who are learning to manage an account for the first time. A complicated budget can make a beginner feel that every purchase needs a perfect category and every month needs a detailed plan. A ledger teaches a more fundamental skill: understand what entered the account, understand what left it, and keep the balance honest. Once that habit is established, a user can decide whether more advanced budgeting tools are necessary.
The app’s age rating of Everyone reinforces its approachable positioning. I would not interpret that as a promise that it suits every financial situation, but it does make sense for a general-purpose personal record rather than a specialist business application. It can be relevant to students, households, older users who prefer checkbook logic, or anyone moving away from paper without wanting a large digital finance suite.
Where the simple design starts to feel limited
The same manual structure that makes the app approachable is its most meaningful weakness. If you have several bank accounts, credit cards, savings goals, investments, or shared household expenses, a basic register may become difficult to maintain. You might be able to keep separate records in your own process, but the mental work grows quickly. At that point, a budgeting platform with automatic synchronization and broader account support may be a better fit.
I would also be cautious about expecting detailed financial analysis. A ledger tells me what I recorded; it does not automatically explain why my spending changed or help me design a realistic plan. Someone looking for category trends, debt payoff planning, bill reminders, forecasting, or a broader view of net worth should compare this app with tools built specifically for those jobs.
Manual entry creates another point of friction: consistency. On a good week, recording transactions feels easy. During travel, illness, or a busy family schedule, it is easy to postpone the task. A delayed entry can make the balance look better than it really is, which defeats the main reason for keeping a ledger. I would only choose this model if I were willing to make recording part of my routine rather than treating it as an occasional cleanup task.
There is also a practical difference between a ledger and a bank account. The app should be treated as a personal record, not as an authoritative source of cleared funds. I would still check the bank when making a large payment, confirming a deposit, or investigating a discrepancy. Keeping that distinction in mind prevents overconfidence in a balance that depends on manual updates.
Version, cost, and what to expect before installing
The current version is 3.5, and the app has been available since August 3, 2016. That long presence suggests a product with a clearly defined purpose rather than a brand-new experiment, but I would still judge it by whether its current workflow suits me. Older, focused apps can be appealing because they avoid constant feature expansion; they can also feel less modern than newer financial platforms.
There is no purchase required to start because the app is free. Optional in-app purchases are priced at $1.99 per item. I would view that as a relatively low-cost way to explore the experience, while remembering that the important value is not the price but the time required to keep the ledger accurate. A free app that I stop using after a week is less useful than a paid alternative that automatically keeps my records current.
The minimum operating-system requirement is 11. Before installing, I would check that the device meets that requirement, especially if I am using an older phone or tablet. The app has passed the 100K-plus-install mark and has an average rating of 3.4 from around 2.5K ratings, with roughly 1.2K written reviews. Those figures indicate that people have tried it in meaningful numbers, but they also suggest a mixed experience rather than universal satisfaction. I would read recent user comments for clues about compatibility and workflow before relying on it for important records.
Who should choose it, and who should skip it
I think Simple Checkbook Ledger is a strong match for someone with a straightforward financial setup who wants manual control. It is especially suitable if you:
- Prefer entering transactions yourself instead of connecting accounts.
- Want a digital replacement for a paper checkbook register.
- Need a simple way to monitor one main spending account.
- Are building the habit of checking a balance before spending.
- Find large budgeting apps distracting or unnecessarily complicated.
I would be more hesitant to recommend it to someone who wants automatic transaction imports, extensive account aggregation, or detailed financial planning. It is also not my first choice for a household where several people need to update the same record, unless everyone agrees on a careful process. A shared spreadsheet or a purpose-built household budgeting service may handle collaboration more naturally.
For a small business, freelancer, or anyone needing formal bookkeeping, I would look elsewhere. A personal checkbook ledger can help track cash movement, but it should not be confused with business accounting, invoice management, tax preparation, or expense reporting. The app’s strength is its narrow focus, and that focus becomes a limitation when the financial situation is more complex.
How it compares with familiar alternatives
Compared with a paper register, the app is easier to carry and easier to revise when I make an input mistake. It can also reduce the need to keep a physical notebook nearby. Paper still has one advantage: it is immediate and does not depend on a device. Someone who enjoys writing transactions by hand may not gain enough from switching to justify changing habits.
Compared with a spreadsheet, the app is likely to feel more purpose-built for a running account. A spreadsheet can be customized with formulas, categories, and summaries, but building and maintaining those elements takes effort. I would choose the spreadsheet if I wanted complete control over reports or needed to combine several types of financial information. I would choose this app if I wanted to start recording without designing a system first.
Compared with an automatic budgeting app, the trade-off is clearer. Simple Checkbook Ledger gives me deliberate input and a less crowded experience, while the automatic alternative saves time and can reveal spending across multiple accounts. Neither approach is automatically better. The right choice depends on whether my main problem is lack of control or lack of time. If I forget to record transactions, automation wins. If I feel overwhelmed by connected-account dashboards, the ledger wins.
A workflow I would actually recommend
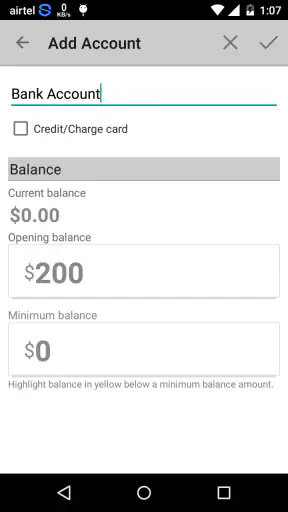
I would begin with one account rather than trying to recreate my entire financial history. Enter the current balance, then record new activity from that point forward. Starting small makes it easier to notice whether I genuinely enjoy the routine. It also avoids spending an evening entering old transactions that may not improve the decisions I make today.
For the first week, I would keep the descriptions consistent and check the balance before making discretionary purchases. At the end of the week, I would compare the ledger with the bank account and look for the first mismatch. That process reveals whether the app fits my habits better than simply reading a feature list. If I repeatedly forget entries, I would not blame the interface; I would take that as evidence that an automatic tool may serve me better.
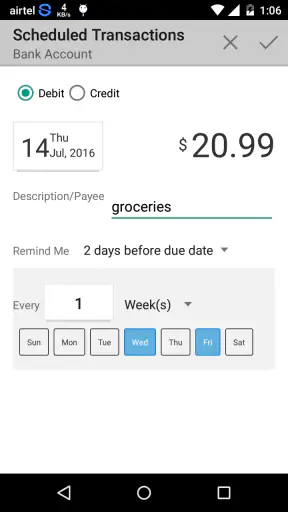
For recurring bills, I would record them as soon as they are scheduled or paid, using the same convention each month. For irregular spending, I would enter the transaction immediately after purchase. For cash, I would record the withdrawal and then treat later cash spending as a separate part of my personal routine. This is a small but important distinction: otherwise, the ledger can show the withdrawal while hiding where the cash actually went.
My final recommendation
After looking at the app as a daily finance tool, I see Simple Checkbook Ledger as a useful specialist rather than a universal solution. It does one central job in a way that can be easier to understand than a feature-heavy budgeting platform. The free entry point, Everyone rating, and straightforward checkbook concept make it approachable for people who want to take responsibility for their own records.
My recommendation is strongest for a person with one or two uncomplicated accounts who will enter transactions consistently. In that setting, the app can turn an uncertain balance into a running record and encourage better awareness of everyday spending. I would skip it if I needed automatic imports, shared real-time budgeting, investment tracking, or serious financial analysis.
The average rating of 3.4 and the broad install base tell me that it has found an audience, but not that it will suit every user. I would try it with a small, low-risk account first, establish a weekly reconciliation habit, and see whether the manual workflow feels sustainable. Its real strength is clarity, and its real cost is the discipline required to preserve that clarity. For the right user, that is a fair trade. For everyone else, a more automated alternative will probably be the better everyday companion.
Frequently Asked Questions
01What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor everyday financial transactions in a straightforward way. You can enter deposits, withdrawals, purchases, and other adjustments, then review your running balance. It is especially useful for people who want a basic digital checkbook without the complexity of full budgeting, investment, or banking applications.
02Does Simple Checkbook Ledger connect directly to my bank account?
Simple Checkbook Ledger is primarily intended for manual transaction tracking rather than automatic bank synchronization. You generally enter transactions yourself, which gives you control over what is recorded and avoids sharing online banking credentials with the app. Before downloading, users who require automatic imports, live account balances, or bank notifications should verify whether their specific version supports those features.
03Can I use Simple Checkbook Ledger for multiple accounts?
The app may be suitable for keeping separate records for different checking accounts, savings accounts, cash funds, or other personal ledgers, depending on the features included in the installed version. This can make it easier to distinguish household finances from personal spending. However, users managing many accounts should check the app’s account limits and organization options before relying on it for detailed financial administration.
04Does Simple Checkbook Ledger provide budgeting and financial reports?
Simple Checkbook Ledger focuses mainly on maintaining an accurate transaction register and calculating balances. It may include basic summaries or categorization tools, but it is not necessarily a complete budgeting platform with advanced charts, bill reminders, forecasting, or investment analysis. If you need detailed spending insights, confirm the available reporting features and consider whether a more comprehensive finance app would better match your needs.
05Is my financial information safe when using Simple Checkbook Ledger?
Because a checkbook ledger can contain sensitive information, you should review the app’s privacy policy, permissions, backup options, and security settings before entering real financial details. Manual tracking can reduce the need to provide bank login credentials, but it does not automatically guarantee complete protection. Use a device lock, keep the app updated, and avoid storing unnecessary account numbers or other highly confidential information.


